Negotiating Note Prices: Why Messy Seller Data Pays
How to negotiate a better price on a mortgage note: find sellers with messy loan data, build the tape yourself and price from what other buyers skip.
Why Do the Best Deals Come from the Worst Data?
There is a saying in note investing that sellers should live by: minimize uncertainty to maximize value. A seller who presents clean data, organized tape files, and thorough documentation makes it easy for buyers to evaluate the assets -- and easy evaluations attract competitive bids. More competition pushes prices higher. The seller wins.
But as a buyer, the opposite principle applies. Bring on the uncertainty. When a seller's data is incomplete, disorganized, or difficult to interpret, most buyers move on to the next deal. They do not want to sift through PDF printouts of loan statements, reconstruct spreadsheets from scattered documents, or piece together collateral files that arrive in no particular order. That reluctance is your edge.
The tip is deceptively simple: look for the deals that other buyers will not bother to work through, and then do the work. The arbitrage lives in the gap between what the data looks like on the surface and what the assets are actually worth once you have organized and analyzed the information yourself.
Recognizing Seller Disorganization When You See It
Not every messy deal looks the same. The level of disorganization varies widely depending on the type of seller you are working with, and recognizing the patterns helps you move quickly when you see an opportunity.
The Community Bank with No Secondary Market Experience
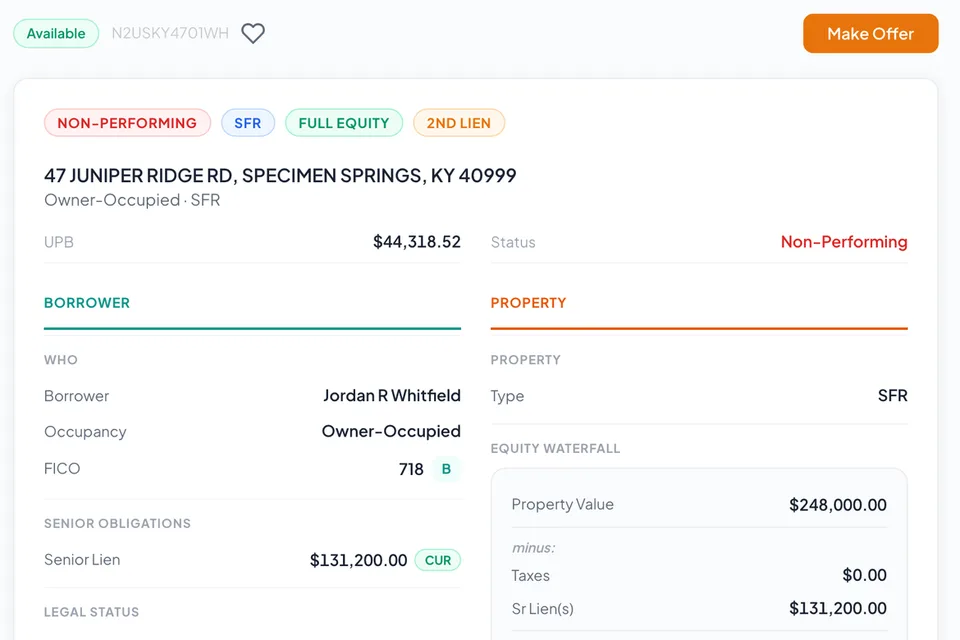
A small community bank or credit union that has never sold loans on the secondary market probably does not have a formatted data tape ready for distribution. They may not even know what a tape is in the context of a loan sale. Instead of a spreadsheet with standardized fields -- unpaid principal balance (UPB), interest rate, payment status, property value, borrower information -- you might receive:
- PDF exports from their loan servicing system
- Printouts of individual account statements
- A mix of documents across different formats and naming conventions
- Incomplete fields where data was never tracked in a way that translates to secondary market analysis
This is not a problem. It is a signal. A seller who cannot produce a clean tape probably isn't working with other secondary market buyers. You may be the only person evaluating these assets, which means you are not competing on price. That alone changes the economics of the deal dramatically.
The Distressed Seller Offloading a Portfolio
Sometimes a seller is motivated by factors that have nothing to do with maximizing sale price. They might be under regulatory pressure to reduce non-performing assets on their balance sheet, dealing with an internal restructuring, or simply trying to close out a line of business. In these situations, the data quality often reflects the seller's urgency -- they want the loans gone more than they want to spend time packaging them neatly for buyers.
When you encounter a seller in this position, the disorganized data is a feature, not a bug. Their urgency combined with their lack of preparation creates a window where a buyer who can move quickly and work through the mess has a real advantage.
The Private Lender with a Handful of Notes
Private lenders or individuals who hold a small number of notes often keep records in ways that would make an institutional seller cringe. Handwritten ledgers, emails with payment confirmations, and incomplete files stored across multiple locations are all common. For a buyer willing to organize this information into a usable format, these one-off sellers can be some of the most profitable sources of deal flow -- precisely because no institutional buyer will touch the operational overhead of reconstructing the data.
How Does Messy Data Create Pricing Arbitrage?
The concept of arbitrage in note investing is not about finding a secret price that nobody else knows. It is about information asymmetry -- knowing more about the assets than the next bidder, and using that knowledge to price accurately while others are guessing or walking away.
When a seller distributes a clean, well-organized tape to their buyer network, every bidder has access to the same data. They can all run the same formulas, pull the same property values, and arrive at similar pricing conclusions. The result is tight bid spreads and competitive pricing that compresses margins for buyers.
When the data is disorganized, the playing field tilts. Most buyers will either pass on the opportunity entirely or submit a lowball indicative bid that reflects their uncertainty about the assets. They are pricing in the unknown because they are unwilling to do the work to reduce it.
If you do the work -- if you take those PDF statements and rebuild them into a spreadsheet, verify the key data points, and run your pricing model against real numbers instead of assumptions -- you can submit a bid that is both more competitive than the lowball offers and more profitable than what you would achieve on a polished tape with ten other buyers at the table.
That gap between what the lazy bid looks like and what the informed bid looks like is where the arbitrage lives.
Turning Disorganized Data into a Pricing Advantage
Converting a pile of unstructured documents into actionable pricing requires a systematic approach. Skipping steps or cutting corners defeats the entire purpose -- you are doing this work specifically because other buyers will not.
Step 1: Build the Tape Yourself
Start by creating a blank spreadsheet with the standard fields you need for pricing: loan number, borrower name, property address, state, UPB, interest rate, monthly payment, next due date, lien position, property value, senior lien balance (for junior liens), occupancy status, and any other data points your pricing model requires.
Then populate it. Go through each document the seller provided and extract the relevant data points into the corresponding columns. This is tedious work, especially on portfolios with more than a handful of loans. But the act of manually entering the data forces you to read every statement, notice discrepancies, and identify loans that warrant closer attention -- benefits you would miss if you were simply scanning a pre-formatted tape.
Step 2: Validate the Numbers
Once the data is in spreadsheet form, run basic validation checks:
- Does the UPB make sense relative to the original loan amount? A loan originated at $150,000 showing a UPB of $148,000 after fifteen years of payments raises questions about negative amortization or data entry errors.
- Are the interest rates within normal ranges? A stated rate of 18% on a first-lien mortgage is unusual enough to warrant verification.
- Do the property addresses resolve to real properties? A quick search confirms the property exists and gives you a starting point for value estimation.
- Is the payment history consistent with the stated delinquency? A loan showing 24 months delinquent but with a last payment date from five years ago has a data conflict that needs resolution.
These checks are not due diligence in the full sense -- you are not ordering title searches or BPOs at this stage. You are cleaning the data enough to price accurately and identify the loans that need deeper investigation before you commit capital.
Step 3: Run Your Pricing Model
With a clean tape in hand, apply whatever pricing framework you use for indicative bids. Whether you price off a percentage of UPB, a stratified matrix based on lien position and equity, or a resolution-based model that projects outcomes and works backward to a purchase price (the approach in how to value an NPL to make an offer), the mechanics are the same as they would be for any other tape. The difference is that you built the input data yourself, which means you understand its limitations and strengths better than a buyer who simply received a formatted spreadsheet from the seller.
Step 4: Identify the Hidden Value
The process of reconstructing the data often surfaces information that would be invisible on a standard tape. You might discover:
- A loan with significantly more equity than the seller realized. If the seller has not updated property values in years, your own research using free automated valuation models might reveal that LTV (loan-to-value) ratios have improved substantially since the loan was originated or last reviewed.
- A borrower who is actually in a position to resolve. Payment history patterns, even partial ones, can indicate whether a borrower went through a temporary hardship (job loss, medical event) versus a permanent inability to pay. Temporary hardships are more likely to resolve favorably.
- Collateral file strengths that reduce risk. If the seller's documents include original notes, recorded mortgages, and clean assignment chains, you have a stronger legal position than the disorganized presentation might suggest.
- Loans that should be excluded. Not every loan in a disorganized portfolio is worth buying. Some may have statute of limitations exposure, missing documentation that cannot be reconstructed, or other defects that make them unpriceable. Identifying these early lets you exclude them from your bid or price them at nominal value, which brings your blended offer down to a level that reflects the real portfolio quality.
How Should You Price When You Are the Only Buyer?
When your work has confirmed that you are likely the only serious bidder -- because the data was too messy for anyone else to bother with -- your pricing strategy shifts in important ways.
Anchor Conservatively
Without competitive pressure forcing your bids higher, you have the luxury of starting conservative. If your pricing model says a portfolio is worth 50-55 cents on the dollar, consider leading with an initial analysis at 35-40 cents. This is not about trying to steal assets from the seller. It is about creating room to negotiate upward -- a dynamic that feels collaborative rather than adversarial.
When you come back after deeper analysis and sharpen your pencil to 48 cents, the seller perceives that as a positive progression. You moved in their direction. Compare that to starting at 55 cents and having to negotiate downward after due diligence reveals problems -- a dynamic that erodes trust and can kill the deal.
Factor in Your Effort
The time and effort you invested in reconstructing the data has real value, and it should be reflected in your pricing. You are not paying the same price as a buyer who received a clean tape and spent thirty minutes running formulas. You spent hours -- possibly days -- building the analytical foundation from scratch. Your knowledge of these assets is deeper, your risk assessment is more granular, and your confidence in the pricing is higher. That effort entitles you to better margins, and the lack of competition makes those margins achievable.
Think About the Relationship, Not Just the Transaction
Sellers who have never participated in a secondary market trade are often the beginning of a long-term relationship, not a one-time deal. A bank that sells you a pool of non-performing loans today might have another pool next quarter, and another the quarter after that. If you treat the first transaction as an opportunity to demonstrate professionalism, transparency, and fair dealing (a no-risk bid structure helps a first-time seller say yes), you position yourself as the buyer they call first -- before the loans ever reach the broader market.
This long-term perspective should influence your pricing. Paying a few points more than your absolute floor on the first deal, in exchange for preferred access to future deal flow, is often the right trade. A recurring seller relationship can be worth far more than the incremental margin on a single portfolio.
Negotiation Tactics That Work with Disorganized Sellers
Negotiation with an unprepared seller requires a different playbook than bidding on a competitive tape. The seller may not have benchmarks for what their loans are worth, may not understand secondary market conventions, and may have unrealistic expectations based on the face value of their receivables.
Educate Before You Negotiate
Before discussing price, invest time in helping the seller understand how secondary market pricing works. Explain why a non-performing loan does not trade at par. Walk them through the relationship between property value, lien position, and recovery probability. Show them how delinquency history and borrower profile affect pricing.
This is not charity -- it is strategic. A seller who understands the pricing framework is far more likely to accept a reasonable offer than one who compares your bid to the UPB on their balance sheet and sees a 50% discount as an insult. Education reduces the friction that kills deals.
Use Data to Support Every Number
When your bid is lower than the seller expected, back it up with evidence. Share the property values you found, the comparable sales data, the occupancy information, and any risk factors you identified during your analysis. A bid supported by data is far harder to dismiss than a number that appears to have been pulled out of thin air.
This transparency also builds credibility. When the seller sees that you have done more work analyzing their portfolio than they did maintaining it, they recognize that you are a serious counterparty -- not a speculator looking for a quick flip.
Be Ready to Walk
Not every disorganized seller will agree to a price that makes sense for you. Some sellers have unrealistic expectations that no amount of education or evidence will change. When that happens, be willing to walk away. Leave the door open -- "If your situation changes or you want to revisit this down the road, I would be happy to take another look" -- but do not chase a deal past the point where the economics work.
Walking away is especially powerful with exclusive sellers because it forces them to confront the reality that finding another buyer willing to do the work you did is not guaranteed. Some sellers who reject an offer come back weeks or months later, ready to transact on terms closer to what you originally proposed.
How Do You Build a Repeatable System for Finding These Deals?
The best note investors do not stumble into disorganized sellers by accident. They build systems that consistently surface these opportunities.
Direct Outreach to Non-Market Sellers
Community banks, credit unions, and private lenders that have never sold loans on the secondary market will not appear on any broker's distribution list. Finding them requires direct outreach -- phone calls, emails, networking at industry events, and building relationships with people who can make introductions. This is time-intensive work that most buyers will not do, which is exactly why it produces the best deal flow.
Relationships with Brokers Who Handle Off-Market Deals
Some note brokers specialize in sourcing from sellers who are new to the secondary market. These brokers often bring you deals with raw, unformatted data because that is how the seller provided it. Building relationships with these brokers -- and demonstrating that you can work with messy data and close deals -- puts you on the short list for future offerings.
Tracking and Follow-Up
Not every conversation with a potential seller leads to an immediate deal. Maintain a database of sellers you have contacted, the status of each relationship, and the next follow-up date. The seller who was not ready to sell six months ago may be under entirely different circumstances today. Consistent, professional follow-up turns cold leads into warm opportunities over time.
The Structural Advantage Most Buyers Cannot Replicate
The reason this tip works is the same reason most buyers will never use it: it requires effort that does not scale neatly. Institutional buyers with large teams and standardized processes are optimized for clean tapes and competitive bids. They cannot justify the operational cost of reconstructing data for a single portfolio when they have dozens of formatted tapes to evaluate in the same timeframe.
That structural limitation is your competitive moat. As an individual investor or small fund operator, your willingness to do manual, unglamorous work on a single deal is precisely what larger buyers cannot replicate. The deals that are too small, too messy, or too labor-intensive for institutional capital are where individual investors have the best chance of finding better risk-adjusted returns.
The next time a seller sends you a stack of PDFs instead of a clean spreadsheet, do not delete the email. Open the files, start building the tape, and recognize that the very thing making your job harder is what makes the deal better.
 Free Note Investor Workshop
Learn notes by pricing one.
Analyze a training loan modeled on a real deal, then submit practice offers on loans that actually sold.
- No credit card
- No email needed to start
- 7 steps · about 70 min