Note Investing Tools: The Stack and Network You Need
The note investing tools every investor needs, by category (CRM, title research, property data, credit, skip tracing, e-signature) and the network.
What Does the Note Investor's Toolkit Actually Look Like?
A mortgage note business runs on information. Every loan you evaluate, every borrower you contact, every county you research, and every deal you close depends on pulling the right data from the right source at the right time. The difference between an investor who closes deals efficiently and one who drowns in spreadsheets is not intelligence or experience alone -- it is the infrastructure they have built around their workflow.
That infrastructure is a combination of software tools, data services, professional networks, and communication systems. None of them are optional once you move beyond your first handful of loans. And while specific product names change over the years -- platforms get acquired, pricing shifts, new entrants appear -- the categories of tools you need remain remarkably stable.
Whether you are building your first system or auditing one that has grown organically over several years, the goal is the same: a connected ecosystem where data flows between tools rather than sitting in isolated silos.
Why Does a CRM Matter More Than a Spreadsheet?
Early in a note investing career (the stage our complete guide to investing in mortgage notes walks through), most people manage everything in Excel or Google Sheets. That works when you have five loans and ten contacts. It stops working when your portfolio grows, because spreadsheets are flat -- they do not connect related data in meaningful ways.
A customer relationship management platform solves this problem by linking records together. Your borrower contact connects to their loan record. That loan record connects to the county where the property sits. The county record links to the state-level data about foreclosure timelines, recording requirements, and tax sale rules. When you open a single loan record, every piece of related information is accessible from that one screen.
The category of tool matters more than the specific product. What you need from a CRM for note investing includes:
- Customizable fields -- mortgage note data does not fit neatly into a standard sales CRM. You need fields for unpaid principal balance, lien position, occupancy status, servicing transfer dates, and dozens of other loan-specific attributes.
- Relational data -- the ability to link contacts, loans, counties, states, vendors, and documents to each other so that navigating between related records takes one click.
- Mobile access -- borrowers call at unexpected times. Being able to pull up a loan record from your phone while taking a call means you can communicate intelligently without being chained to your desk.
- Import and export -- you will receive tapes as spreadsheets and need to import them. You will need to export data for your CPA, your loan servicing company, or your investors.
- Automation hooks -- the ability to connect your CRM to other web services through APIs or integration platforms, so that data entry happens once and propagates everywhere it needs to go.
The right choice depends on your technical comfort level, your budget, and how much customization you need. The wrong choice is no CRM at all.
Building a Connected Data Environment
The real power of a CRM is not the tool itself -- it is how it connects to everything else in your operation. A well-designed note investing workspace links several layers of data that would otherwise live in separate, disconnected systems.
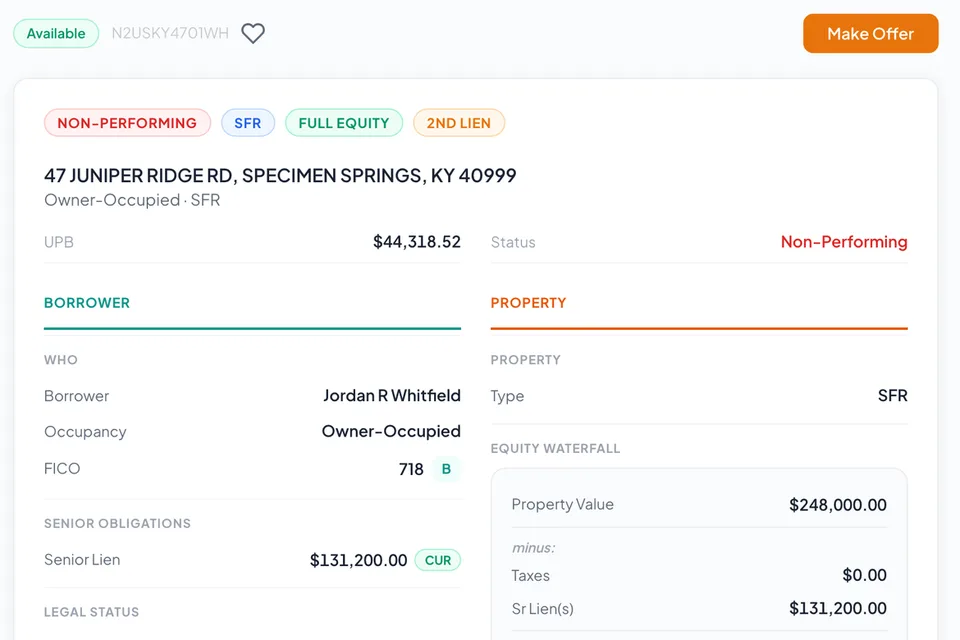
Portfolio data sits at the center. Each loan record contains the core attributes you track from acquisition through resolution: borrower information, property details, lien position, balance, payment history, resolution status, and exit strategy.
Geographic data surrounds the portfolio layer. Every property sits in a county, and every county has its own public records system, tax collector, recording office, and foreclosure process. Building a database of county-level information -- links to online public records, tax collector phone numbers, recorder contact details, and recording requirements -- means that when you need to research a property or record an assignment, the starting point is already documented.
State-level data provides the legal and regulatory context. Judicial or non-judicial foreclosure? Typical timeline? Deed of trust or mortgage state? Super-lien provisions? These attributes rarely change, so documenting them once creates a permanent reference layer that informs every deal in that state.
Contact data connects people to loans. Borrowers, attorneys, servicers, title companies, brokers, and investors all relate back to specific assets or transactions. When your contacts are linked to the loans they touch, you can see the full history of every interaction without searching through email threads.
Document data closes the loop. Every loan has a collateral file -- the original note, mortgage, assignments, allonges, and any recorded modifications. Linking scanned documents to the loan record means the file is always one click away from the data it supports.
When these layers are connected, you stop asking "where is that information?" and start asking "what should I do next?"
What Title Research Tools Should You Use?
Title research is one of the most critical components of due diligence, particularly for first-position liens. An ownership and encumbrance report -- commonly called an O&E report -- tells you who owns the property, what liens are recorded against it, whether the assignment chain is intact, and what the property tax status looks like. Without this information, you are buying a loan blind.
The tool categories for title research include:
Professional title search services. These are companies that employ abstractors to research county records and compile a report on the property's title position. The output is typically a PDF summarizing the chain of title, all recorded liens, property tax status, and any active judgments. Some services also deliver the data in spreadsheet format, which is invaluable when you are analyzing assets in bulk -- ten or more loans at a time benefit significantly from having title data in a filterable, formula-friendly format rather than individual PDFs.
County public records portals. Many counties now offer online access to their recorded documents -- deeds, mortgages, assignments, satisfactions, and liens. If you are willing to do your own abstracting work, these portals let you research a property's title position at no cost. The tradeoff is time: a professional abstractor can compile in hours what might take you a full day if you are unfamiliar with a particular county's record system.
Property tax research tools. Confirming that property taxes are current is essential for senior lien investors. When you buy a first-position mortgage, the main claim ahead of you in priority is the property tax lien (in some states an HOA super-lien or certain municipal liens can also jump ahead). Delinquent taxes that go unaddressed can end in a tax sale that wipes out your mortgage position entirely. Some title search services include tax status in their reports. When they do not, you need a separate source -- either the county tax collector's website or a data provider that aggregates tax records across jurisdictions.
The decision of when to order a professional title search versus doing the research yourself depends on the value of the asset and the stage of your due diligence. For high-value senior liens, a professional report is almost always worth the cost. For lower-balance junior liens where the senior is current and equity coverage is strong, a manual review of county records online may suffice.
Data Providers for Bulk Due Diligence
When you receive a tape with twenty or fifty loans, you need data at scale. Manually researching each property one at a time through free public sources is not feasible when you are trying to submit a bid within a competitive timeframe.
Bulk data providers fill this gap by offering property data, valuation estimates, ownership records, and lien information across large portfolios. The categories of bulk data tools include:
- Property data platforms -- services that aggregate property characteristics, ownership history, comparable sales, and automated valuation models across millions of properties. When you upload a list of addresses, these platforms return enriched data that would take hours to compile manually.
- Automated valuation models (AVMs) -- algorithmic property value estimates based on comparable sales, property characteristics, and market trends. AVMs are not substitutes for a broker price opinion or manual comp analysis, but they provide a fast baseline for initial screening.
- Credit reporting services -- pulling a borrower's credit profile (a potential investor in an existing loan has a permissible purpose under 15 U.S.C. §1681b(a)(3)(E)) gives you insight into their overall financial picture, including other debts, payment history, and bankruptcy filings. This information helps you assess whether a borrower is likely to engage in a workout or whether foreclosure is the more probable resolution path.
The key principle is matching the tool to the stage of your analysis. Bulk tools for initial tape screening. Individual, more detailed lookups for deep dives on the loans you are seriously considering.
How Does Skip Tracing Fit Into the Workflow?
Skip tracing is the process of locating a borrower who is not responding to standard communication attempts. In the non-performing loan space, skip tracing is not an edge case -- it is a routine part of the collections workflow. Many borrowers on non-performing loans have moved, changed phone numbers, or simply stopped opening mail from their previous lender.
Skip trace data providers aggregate public records, utility connections, phone databases, and other sources to produce updated contact information for an individual. The output typically includes:
- Current and previous addresses -- useful for confirming whether the borrower still occupies the property or has relocated.
- Phone numbers -- landline and mobile numbers associated with the borrower, often ranked by recency and confidence level.
- Email addresses -- secondary contact channels that can supplement traditional mail and phone outreach.
- Associated individuals -- relatives, neighbors, or co-borrowers who may be able to help you reach the primary borrower.
Skip tracing is most effective when used early in the collections process. When you acquire a non-performing loan and your loan servicing company sends the initial hello letter, having updated contact information from a skip trace increases the probability that the letter reaches the borrower and that follow-up calls connect.
Collection communication is regulated: debt collectors fall under the Fair Debt Collection Practices Act and the CFPB's Regulation F, and mortgage servicers under RESPA's Regulation X. Skip trace data gives you the means to reach a borrower, but how and when you use that data is governed by those rules. If you are working with a loan servicer or licensed debt collector, they should be managing compliance on your behalf -- but auditing their practices is your responsibility as the loan owner.
Communication Tools That Keep Your Operation Professional
Communication infrastructure is easy to underestimate. It is not glamorous, and the tools themselves are simple. But how you communicate with borrowers, vendors, investors, and counterparties defines your professionalism and your legal exposure.
The communication stack for a note investor includes:
Email. Your primary channel for vendor communication, investor updates, and documented borrower correspondence. A platform that supports templates, scheduling, and organized threads saves time and ensures consistency. If you or your servicer are a debt collector under the FDCPA, the first written communication must disclose that you are attempting to collect a debt and any information obtained will be used for that purpose, and later communications must say they come from a debt collector (15 U.S.C. §1692e(11)).
Document execution. When you need a borrower to sign a modification agreement, a seller to execute an assignment, or an investor to sign a subscription document, electronic signature tools eliminate the delays and costs of physical mail. The ability to send, track, and store executed documents digitally is a baseline requirement for a modern note operation.
Phone and text. Borrower outreach often requires direct conversation. Some borrowers prefer text communication over phone calls. Respecting the borrower's preferred communication channel -- when legally permissible -- improves engagement rates. Debt collectors may not contact a borrower before 8 a.m. or after 9 p.m. in the borrower's local time (15 U.S.C. §1692c(a)(1)), and autodialed or prerecorded calls to a cell phone need the borrower's prior express consent (47 U.S.C. §227(b)).
Spreadsheet and document tools. Loan tapes arrive as spreadsheets. Investor reports are built in spreadsheets. Purchase and sale agreements start as document templates. Proficiency with spreadsheet formulas -- calculating yields, amortization schedules, and portfolio-level metrics -- is a non-negotiable skill and one of the most practical competitive advantages a note investor can build.
How Do You Build Your Professional Network?
Tools handle data. Networks handle relationships. And in the mortgage note business, relationships drive deal flow, capital access, vendor quality, and knowledge transfer.
The network categories that matter for note investors are:
Seller relationships. Your acquisition pipeline depends on maintaining connections with banks, hedge funds, brokers, and other investors who sell loans. A single seller relationship can generate years of deal flow if you are a reliable closer who performs due diligence quickly and funds on time. Building a reputation as a professional buyer -- someone who submits clean bids and closes when they say they will -- is the most effective marketing strategy in this business.
Vendor relationships. Attorneys, title companies, servicers, property preservation vendors, and local contractors form the operational backbone of your business. The quality of your vendors directly affects your resolution timelines, costs, and legal exposure. Building a roster of trusted vendors in your target markets -- and having backups when a primary vendor is unavailable -- takes time but pays dividends at scale.
Investor relationships. If you fund acquisitions with outside capital, your investor network is the engine of your growth. Raising capital requires trust, and trust requires consistent communication, transparent reporting, and demonstrated competence. A regular reporting cadence with standardized templates is the minimum.
Peer relationships. Other note investors are simultaneously your competitors and your most valuable source of industry knowledge. Conferences, mastermind groups, and online forums create relationships with peers who share market intelligence, co-invest on larger deals, or buy loans from your portfolio that do not fit your strategy.
The network effect in note investing is real. The more people in the industry who know and trust you, the more opportunities flow in your direction without active marketing.
The Integration Layer That Connects Everything
Individual tools are useful. Connected tools are transformative. The integration layer -- the set of automations and data flows that link your tools together -- is what turns a collection of software into an operational system.
Integration platforms allow you to connect web services without writing code. When a new loan is added to your CRM, an automation can create a task to order a title search. When a borrower makes a payment through your servicer, the payment data can flow back into your CRM and update the loan record automatically.
The principle behind integration is simple: enter data once, and let the system propagate it everywhere it needs to go. Every time you copy a number from one spreadsheet to another, you introduce the possibility of error. Every time you manually check a status that could be updated automatically, you waste time that compounds across hundreds of loans.
Start with the highest-friction manual tasks -- the ones you perform most frequently or the ones most prone to error -- and automate those first. Over time, the integration layer grows to cover more of your workflow, and the manual effort required to run your operation decreases.
Evaluating and Adopting New Tools
The note investing tool landscape evolves. New platforms launch. Existing platforms change pricing or get acquired. AI-powered tools create capabilities that did not exist a few years ago. The question is not whether to adopt new tools -- it is how to evaluate them without constantly disrupting your workflow.
A practical evaluation framework asks four questions:
- Does it solve a real friction point? If you are not currently experiencing a problem that the tool addresses, you do not need it.
- Does it integrate with your existing stack? A tool that requires manual export and import is adding work, not reducing it.
- What is the migration cost? Switching CRMs or data providers involves transferring data, retraining your workflow, and accepting a temporary productivity dip.
- Is it built for your scale? A tool designed for institutional investors managing 10,000 loans may be overkill for a portfolio of fifty. Match the tool to your current and near-term future scale.
The investors who build durable operations are not the ones chasing every new product. They build a stable core system and then selectively add capabilities when a clear need emerges.
Connecting Your Entity Structure to Your Tools
One often-overlooked dimension of the tool ecosystem is how it maps to your entity structure. If you operate through an LLC, a fund, or multiple entities, your tools need to reflect that structure. Your CRM should track which entity owns which loans. Your document templates should pull the correct entity name and address. Your accounting should reconcile at the entity level, not just the portfolio level. Building this into your system from the beginning is dramatically easier than retrofitting it later.
Assembling Your Stack: A Category Checklist
Rather than recommending specific products that may not exist or may have changed by the time you read this, here is the category checklist for a complete note investing tool stack:
| Category | Function | Priority |
|---|---|---|
| CRM / Data Management | Portfolio tracking, contact management, relational data | Critical |
| Title Research | O&E reports, chain of title verification, lien search | Critical |
| Property Data / AVMs | Bulk valuation, property characteristics, comp analysis | Critical |
| Credit Reporting | Borrower financial profile, bankruptcy status | Critical |
| Skip Tracing | Updated borrower contact information | High |
| Document Execution | Electronic signatures, document tracking | High |
| Spreadsheet / Analysis | Tape analysis, amortization modeling, yield calculations | Critical |
| Email / Communication | Borrower outreach, investor reporting, vendor coordination | Critical |
| Integration Platform | Connecting tools, automating data flows | High |
| Backup / Security | Data protection, access control, disaster recovery | Critical |
The stack does not need to be expensive -- many categories have free or low-cost options that are perfectly adequate for small portfolios. What matters is that every category is covered and that the tools talk to each other rather than operating in isolation. Build the system once, refine it as you grow, and let the infrastructure carry the operational load so you can focus on the analysis, negotiation, and relationship-building that generate returns.
 Free Note Investor Workshop
Learn notes by pricing one.
Analyze a training loan modeled on a real deal, then submit practice offers on loans that actually sold.
- No credit card
- No email needed to start
- 7 steps · about 70 min