Note Investing Automation: 5 Workflows Worth Automating
Note investing automation that removes manual bottlenecks: the five workflows worth automating, how to pick a platform, and what to keep manual.
Why Should Note Investors Care About Automation?
A mortgage note business generates a surprising volume of repetitive, time-sensitive tasks. Every loan in your portfolio produces status changes that require action: a borrower makes a payment, a bankruptcy filing triggers a proof of claim deadline, a senior lien goes delinquent, a modification agreement needs to be generated. When you hold three loans, you can manage all of this manually. When you hold thirty or three hundred, manual processes become the constraint that limits your growth.
Automation is not about replacing your judgment. It is about eliminating the manual steps between a triggering event and the action that event requires. When a loan servicing company reports a payment received, that information should flow into your portfolio tracker without you copying it from an email. When a new tape hits your inbox, the initial screening data should populate your evaluation framework without you building a spreadsheet from scratch. When a borrower's status changes in your CRM, the downstream tasks -- updating your servicer, generating correspondence, flagging the loan for review -- should initiate automatically.
The investors who build these automated connections between their tools free themselves to focus on the work that actually requires human decision-making: evaluating deals, negotiating with borrowers, managing attorney relationships, and building their investor network. The mechanical work -- data entry, status updates, notification routing, document assembly -- is where automation delivers its highest return on investment.
The Five Core Workflows Worth Automating
Not every process in a note business should be automated. The highest-value automation targets share three characteristics: they happen frequently, they follow a predictable pattern, and a delay in execution creates risk or cost. Across most note operations, five workflow categories meet all three criteria.
Deal Flow Notifications
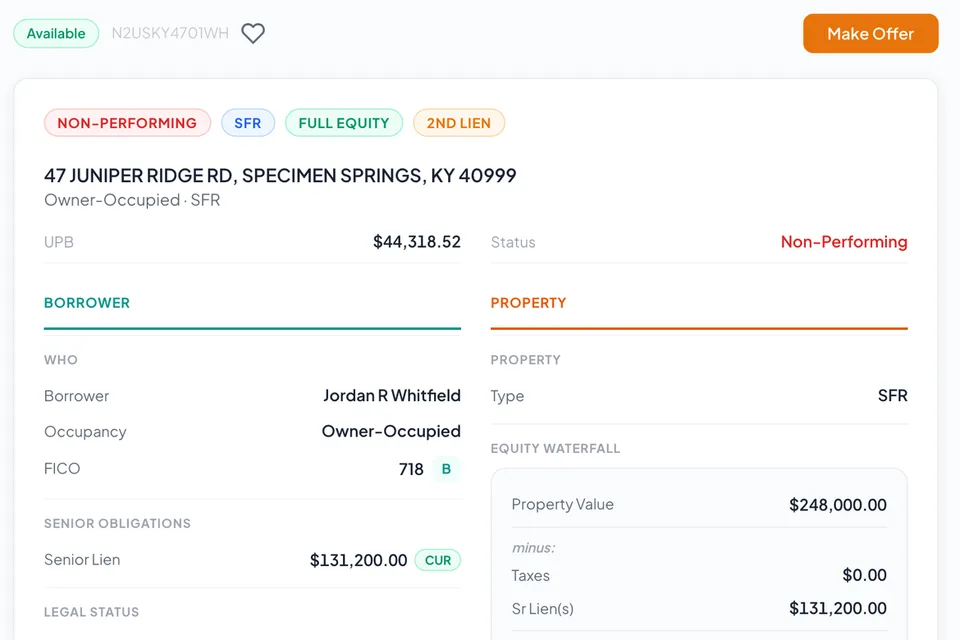
Consistent deal flow is the engine that feeds your acquisition pipeline. Tapes arrive from multiple sources -- brokers, direct sellers, industry platforms, email lists -- and the speed at which you respond often determines whether you get a serious look at the assets. An automated deal notification workflow captures incoming opportunities from every source and routes them into a single pipeline with the context you need to evaluate priority.
The principle is straightforward: every channel where you receive deal flow should feed into one centralized system. When a seller emails a tape, when a marketplace posts new inventory, or when a broker sends a message through an industry platform, the automation captures that event and creates a standardized intake record. It tags the source, logs the date, and flags it for your review. No more scanning three email accounts, two messaging platforms, and a shared drive to figure out what arrived this week.
The more advanced version of this workflow includes initial screening. If the tape arrives as a spreadsheet attachment, automation can parse the data and surface key metrics -- total UPB, geographic distribution, lien position breakdown, average loan size -- before you ever open the file. That ten-second summary tells you whether the tape deserves fifteen minutes of your attention or can wait until you clear your priority queue.
Borrower Status Changes
Once you own a loan, the borrower's behavior drives your resolution strategy. Every status change -- from non-performing to modified, from modified to re-performing, from re-performing to re-defaulted, from active to bankruptcy-filed -- triggers a different set of actions. These status-driven workflows are among the most valuable automation targets in a note business because a missed status change can cost you money or legal standing.
Consider what happens when a borrower who signed a loan modification misses their third consecutive payment. That re-default triggers a cascade of decisions: Do you attempt re-engagement? Do you escalate to your attorney? Do you notify your servicer to update the collections status? Do you update your portfolio tracker and investor reports? In a manual process, you discover the re-default when you review your servicer's monthly remittance report -- possibly weeks after the third missed payment. In an automated workflow, the status change triggers an alert the moment your servicer records it, and the downstream tasks queue up without waiting for your monthly review cycle.
The same principle applies to positive status changes. When a borrower begins making payments under a modification, that re-performance needs to be tracked consistently. Automated workflows can monitor payment history data from your servicer and flag loans that have hit key milestones -- three consecutive payments, six months of on-time performance, twelve months of seasoning -- so you can evaluate whether the asset is ready to be sold as a re-performer or held for continued cash flow.
Payment and Financial Alerts
Cash management in a note business requires tracking money flowing in from multiple borrowers through your servicer and money flowing out to attorneys, vendors, recording offices, and property preservation companies. Automated financial alerts ensure nothing falls through the cracks.
On the inbound side, servicer remittance reports should trigger automatic reconciliation against your expected payment schedule. When a billing statement is generated for a borrower, the system should track whether payment arrives within the expected window. If it does not, the delinquency flag should update automatically -- not after you manually compare the billing record to the payment ledger during your next portfolio review.
On the outbound side, vendor invoices, attorney fee requests, and servicer fees should flow through an approval workflow that logs each payment at the loan level. This loan-level cost tracking is what allows you to calculate true deal-level profitability rather than approximating it from aggregate accounting data. When your CPA needs year-end figures (see the tax implications of mortgage note investing for what they will ask for), the data is already organized by asset rather than buried in a general ledger that requires weeks of reconciliation.
Document Generation and Routing
A note business generates a high volume of templated documents: letters of intent, purchase and sale agreements, assignments, allonges, demand letters, modification agreements, payoff quotes, and lien releases. Each of these follows a predictable structure where the template is constant and the variables -- borrower name, property address, loan number, balances, terms -- change with each loan.
Document automation replaces the copy-paste-and-proofread cycle with a system that pulls the correct data from your portfolio tracker and populates the appropriate template. When your due diligence process reaches the offer stage, the automation generates a letter of intent pre-filled with the asset details from your analysis. When a loan closes and needs to be boarded with your servicer, the loan boarding package assembles automatically from the data already in your system.
The routing component is equally important. Once a document is generated, it needs to go to the right recipient -- the seller, the borrower, the servicer, the attorney, or the county recorder. Automated routing eliminates the step where you manually attach a PDF to an email, look up the recipient's address, and hit send. The system knows which document types go to which recipients and sends them without waiting for you to get to it on your task list.
Portfolio Monitoring and Escalation
Portfolio monitoring is the operational heartbeat of a note business. Every loan needs regular status checks: Is the senior lien current? Are taxes paid? Is the borrower in active bankruptcy? Has the foreclosure timeline advanced? Is insurance coverage in place? When you hold a handful of loans, you can keep this in your head. When the portfolio grows, monitoring discipline is the first thing that slips -- and the consequences of missed monitoring can range from costly to catastrophic.
Automated monitoring workflows operate on a schedule or trigger basis. A scheduled workflow might pull senior lien status data monthly and flag any loan where the senior mortgage has become delinquent. A trigger-based workflow might fire when your servicer updates a bankruptcy status, automatically queuing the proof of claim checklist and deadline tracker.
The escalation layer is what transforms monitoring from passive observation into active management. When a monitored condition crosses a defined threshold -- three missed payments, a tax sale notice, a bankruptcy discharge hearing date within sixty days -- the system escalates the loan from routine monitoring to active intervention. It assigns the task to the appropriate team member, notifies the relevant attorney, and updates the loan status in your tracker. The escalation happens at machine speed, not at whatever pace you happen to check your spreadsheet.
How Do You Choose the Right Integration Platform?
The automation principles described above are platform-agnostic -- they work regardless of which tools you use to implement them. But the practical reality is that most note investors use a collection of specialized tools that were not designed to talk to each other: a CRM for pipeline management, a servicer portal for loan data, an email platform for communications, a spreadsheet for financial modeling, a document repository for collateral files, and an accounting system for bookkeeping.
Integration platforms bridge the gaps between these tools. They connect applications through APIs and webhooks so that an event in one system can trigger an action in another without manual intervention. The category includes platforms like Zapier, Make (formerly Integromat), n8n, and others that offer no-code or low-code automation builders.
When evaluating an integration platform for your note business, three factors matter most:
Trigger speed. Some automations need to execute instantly -- a borrower status change that triggers an alert cannot wait hours for a polling cycle. Look for platforms that support webhook-based (instant) triggers in addition to scheduled polling. The difference between an instant trigger and a fifteen-minute polling interval can be the difference between catching a critical status change in real time and discovering it during your next manual review.
Breadth of integrations. Your automation is only as useful as the connections it can make. If your CRM, servicer portal, email platform, and document storage all have pre-built integrations on the platform, setup is measured in minutes. If any of your core tools lack a direct integration, you will need to work with webhooks or custom API connections, which increases complexity.
Data handling. Note investing workflows often involve structured data -- spreadsheet rows, loan records, financial calculations. The platform needs to handle data parsing, filtering, and transformation without requiring you to write code. Can it extract a specific field from a servicer report? Can it filter loans by status before triggering a downstream action? Can it format data for input into a different system? These capabilities determine whether your automations are robust or fragile.
An Automated Acquisition Pipeline From Tape to Boarding
The acquisition workflow is where most note investors first feel the pain of manual processes, and it is often the first workflow they automate. A fully connected acquisition pipeline links every step from tape receipt to loan boarding.
Intake. A new tape arrives via email or file share. The automation detects the new file, logs the source and date, and creates an entry in your pipeline tracker. If the tape is in a standard spreadsheet format, the system parses the data and generates a summary of the pool characteristics.
Screening. Based on your predefined criteria -- lien position, geography, UPB range, occupancy status -- the automation flags the loans that match your investment profile. Loans that fall outside your criteria are tagged but deprioritized, so you can still review them if the pipeline is thin, but your attention is directed to the highest-probability matches first.
Due diligence tracking. As you move loans through the evaluation process, status updates in your tracker trigger the next steps automatically. When you mark a loan as "BPO ordered," the system logs the order date and sets a follow-up reminder. When the BPO arrives, it updates the property value in your model. When you mark a loan as "bid submitted," the system generates the letter of intent from your template.
Closing and boarding. After purchase, the automation generates the document checklist for the collateral file, creates the servicer boarding package, and schedules the assignment recording with your document control process. The loan appears in your portfolio tracker with all the acquisition data already populated, ready for the monitoring workflows to take over.
Each of these steps can be built incrementally. You do not need to automate the entire pipeline on day one. Start with the step that creates the most friction -- for many investors, that is the intake and screening phase where tapes pile up unreviewed -- and expand from there.
How Do You Avoid Over-Automating?
Automation creates real efficiency gains, but it also creates real risks when applied to the wrong processes. The goal is not to automate everything. The goal is to automate the mechanical steps while preserving human judgment at the decision points.
Three areas of a note business should remain manual, regardless of how sophisticated your automation becomes:
Pricing and bid decisions. No automation should submit a bid on your behalf without your review. The data aggregation, screening, and scoring that inform your pricing model can be automated. The final decision to commit capital cannot. Every deal has nuances that a rule-based system will miss -- seller relationship dynamics, portfolio strategy considerations, market timing factors -- that require your judgment.
Borrower negotiations. Automated outreach can handle initial contact attempts and follow-up scheduling. The actual negotiation of modification terms, discounted payoffs, or workout agreements requires human empathy, legal awareness, and strategic thinking. Automating borrower communication beyond the templated initial touchpoints risks damaging relationships and creating compliance exposure.
Legal strategy. Foreclosure decisions, bankruptcy responses, and litigation strategy involve state-specific legal nuances and case-by-case judgment calls. Automation can track deadlines, generate reminders, and queue documents for attorney review. It should never make the legal strategy decision itself.
The litmus test for whether a workflow should be automated is simple: if the same set of inputs should always produce the same output, automate it. If the output requires evaluation, context, or judgment, keep a human in the loop and let the automation handle everything up to that decision point.
How Should You Prioritize Your Automation Roadmap?
Building automation across your entire operation is a project that takes months, not days. The sequence matters. Automating a low-friction workflow before a high-friction one wastes effort and delays the return on your investment.
Here is a prioritization framework based on where most note investors experience the greatest time loss and error rate:
| Priority | Workflow | Why It Matters First |
|---|---|---|
| 1 | Borrower status change alerts | Missed status changes create the highest financial risk |
| 2 | Payment reconciliation | Cash tracking errors compound over time and create accounting nightmares |
| 3 | Deal flow intake and screening | Speed to review determines whether you see the best deals |
| 4 | Document generation | Eliminates the highest volume of repetitive manual work |
| 5 | Portfolio monitoring and escalation | Scales your oversight capacity as the portfolio grows |
This sequence front-loads the automations that prevent losses and protect cash flow, then moves to the ones that increase throughput and reduce labor. Your specific priorities may differ based on portfolio size, team structure, and which manual processes are currently causing the most pain. The principle holds regardless: automate the highest-risk, highest-frequency workflows first.
The Compound Effect of Connected Systems
The individual automations described above each deliver standalone value. The compound value emerges when they connect into an integrated system where data flows across your entire operation without manual handoffs.
When your acquisition pipeline automation feeds your portfolio tracker, and your portfolio tracker feeds your monitoring workflows, and your monitoring workflows feed your document generation system, and your document generation system feeds your servicer communication channel -- you have built an operational infrastructure that scales with your portfolio rather than against it. Adding ten loans to your portfolio does not add ten units of manual work. The systems absorb the increase, and your attention stays focused on the decisions that move the business forward.
This is the practical meaning of systematizing your note business. Documentation defines what should happen. Automation ensures it happens without waiting for someone to remember, without human transcription errors, and without the delays that accumulate when every step depends on a person manually initiating the next one.
The note investors who invest time in building this infrastructure early operate at a fundamentally different level of efficiency than those who manage every workflow manually. The gap widens with every loan added to the portfolio. The systems do not get tired, do not forget steps, and do not let status changes sit unnoticed in an inbox. They execute the mechanical work so you can focus on the strategic work -- which is where the returns actually come from.
 Free Note Investor Workshop
Learn notes by pricing one.
Analyze a training loan modeled on a real deal, then submit practice offers on loans that actually sold.
- No credit card
- No email needed to start
- 7 steps · about 70 min