How to Finalize Your Mortgage Note Offer
How to finalize a mortgage note offer — moving from indicative bids to firm pricing, negotiating the LPSA, and managing due diligence contingencies.
What Happens Between an Indicative Bid and a Final Offer?
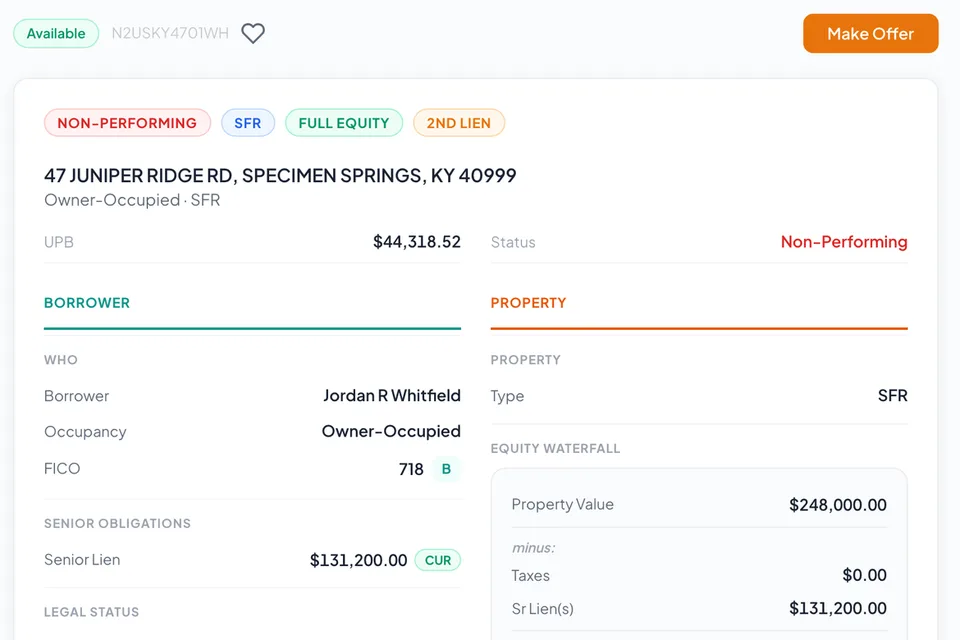
Your indicative bid, priced the way you value an NPL to make an offer, was a hypothesis. It was built on whatever data the seller provided — a data tape, loan statements, perhaps a few supplementary documents — and it reflected your best assessment of what the asset was worth before you spent money verifying anything. Now you have spent 30 days ordering title searches, pulling credit reports, commissioning property valuations, and reviewing collateral files. The gap between what the seller told you and what you have confirmed with third-party evidence is where the final offer takes shape.
Finalizing your mortgage note offer is the process of converting those due diligence findings into a defensible, documented price that reflects verified reality rather than initial assumptions. For some loans in a portfolio, the final number will match or exceed your indicative pricing because everything checked out. For others, the data will tell a different story — and your price needs to follow the data, not the original bid.
This is not a confrontational process. It is the standard workflow that every professional note trade follows. Sellers who have transacted on the secondary market expect pricing adjustments after due diligence. The question is not whether you can adjust — it is whether you do it with documentation, professionalism, and speed.
How Does Due Diligence Create Grounds for Price Adjustments?
Every vendor report you ordered during the due diligence window produces data points that either confirm or contradict the seller's original representations. When they contradict, you have grounds for what the industry calls a "fade" — a downward adjustment to your bid price on a specific loan. The most common triggers fall into several categories, and understanding them is essential for building a credible final offer.
Unsecured Loans
The most severe adjustment happens when a loan represented as secured turns out to be unsecured. If your title search or ownership scrub reveals that the borrower no longer owns the property, the secured collateral backing your investment is gone. You cannot foreclose on a home the borrower does not own. Most buyers remove unsecured loans from the trade entirely, or reprice them at a small fraction of their unpaid principal balance. This is the single most drastic change that due diligence can produce, and sellers who have sold loans before understand that unsecured assets command a fundamentally different valuation.
Equity Discrepancies
Property value and equity are the next most consequential adjustments. Equity can shift from two directions simultaneously: the property may be worth less than the seller's data indicated, and senior liens or unpaid property taxes may be larger than expected. Either one compresses equity. Both together can move a loan from a full-equity position to a partial-equity or even negative-equity position — a material change that directly affects your resolution options and expected returns.
The critical nuance: a property value decline does not automatically justify a fade. If the seller's tape showed the property at $200,000 and your BPO came back at $170,000, but equity was already deep in both scenarios, the value reduction has not changed the risk profile of the loan in any meaningful way. Fading on a technicality when the fundamentals are unchanged is a fast way to erode seller trust. Reserve your equity-based fades for situations where the equity position has genuinely shifted categories — from full to partial, or from partial to negative.
Collateral Defects
During the due diligence window, the seller should provide the original notes, mortgages, assignments, and all supporting origination documents so you can review the chain of title and confirm everything is in order. When documents are missing, the assignment chain is broken, or the title search reveals clouds that need to be cured, the loan falls into what the industry calls a scratch-and-dent category. These loans carry a price discount because resolving collateral defects costs time and money — and the outcome is not always certain.
Borrower and Occupancy Changes
If the seller represented that the borrower was living in the subject property and your research reveals the home is now vacant, that is a legitimate basis for adjusting your price. Owner-occupied properties tend to resolve more often and faster than vacant ones, because a borrower who lives in the home has a personal incentive to work toward a resolution. Similarly, if the borrower's first-position mortgage was reported as current but your credit report shows it has gone delinquent, that signals a deteriorating financial trajectory. A borrower who is falling behind on their senior lien is less likely to prioritize your junior position.
Why Does Documented Evidence Matter When Requesting a Fade?
You cannot call a seller and tell them you have a feeling the property is worth less than expected. That conversation goes nowhere. Every pricing adjustment you request must be backed by a specific vendor report, a specific data point, and a clear connection between the evidence and the price change.
If property value is the issue, provide the BPO or AVM report showing the discrepancy. If senior liens are higher than represented, share the credit report data that confirms the current balance. If the title search revealed unpaid property taxes that were not on the tape, send over the title report showing the tax lien amounts. This documentation serves two purposes: it gives the seller a concrete basis for accepting your adjustment, and it protects the long-term relationship by demonstrating that your fades are grounded in facts rather than negotiation tactics.
Professional sellers often appreciate receiving this evidence because it helps them with their own internal processes. If they need to explain a pricing change to a committee or a board, your supporting documents make that conversation easier for them.
What Is the Right Timeline for Submitting a Final Offer?
Speed matters more than most buyers realize. If the seller gives you 30 days to complete due diligence, and your vendor reports come back in 20 days, do not sit on the results for another 10. Crunch the numbers, compile your adjustments, and send the final offer as soon as your analysis is complete. Sellers notice when a buyer moves quickly through the process — it signals competence and seriousness, and it builds the kind of reputation that produces preferred allocations on future trades.
If there are delays outside your control — title reports taking longer than expected, a vendor backlog, or holiday closures — communicate those delays proactively. A seller who knows you are waiting on a specific report is far more patient than one who is simply not hearing from you. Silence during a due diligence window is the fastest way to make a seller question whether the deal will close.
The goal is to submit your final offer, including any fades and supporting documentation, as a single comprehensive package. Attach the PDFs, the evidence, and a clear explanation of any pricing changes. If it is a pool trade, include a loan-level schedule showing which assets remain at indicative pricing, which have been faded, and which you are removing from the trade entirely.
How Should You Handle Re-Trade Scenarios?
A re-trade occurs when the buyer's final offer comes in materially below the indicative bid. Sellers dislike re-trades because they disrupt the deal timeline, create internal complications, and sometimes indicate that the buyer was not serious about the original price. But re-trades are not inherently adversarial — they are a natural consequence of the due diligence process revealing material differences between represented and verified data.
The distinction between a legitimate re-trade and a bad-faith re-trade comes down to documentation. If your fades are backed by vendor evidence and each adjustment is tied to a specific data discrepancy, the seller can evaluate your position on its merits. If your final offer simply drops across the board with vague justifications, you will damage the relationship and potentially lose the deal.
When Sellers Push Back
Not every fade will be accepted. A seller may counter that their data source was different from yours, that the property value is contested, or that the collateral issue can be cured at their expense before closing. This is a negotiation, and reasonable people can disagree on how much a specific finding should affect pricing. The seller may offer to sharpen their pencil on a few loans in exchange for you holding firm on others. These back-and-forth exchanges are normal. The key is to remain flexible on individual line items while protecting your overall portfolio economics.
Loans to Remove vs. Loans to Reprice
For each problem loan, decide whether it is a candidate for repricing or for removal. An unsecured loan is almost always a removal — the fundamental character of the asset has changed. A loan with a moderate equity fade might simply need a lower price. A loan with a curable title defect might warrant a price reduction that reflects the cost and timeline of the cure. Separating removal candidates from repricing candidates makes your final offer easier for the seller to process and negotiate.
What Should You Review in the Loan Purchase and Sale Agreement?
While your seller is reviewing your final pricing, you should be reviewing the LPSA (loan purchase and sale agreement). This is the contract that governs the trade, and understanding its terms before you sign prevents surprises at closing and after.
Representations and Warranties
The representations and warranties section is the most important part of the LPSA. This is where the seller formally states what they are representing about the loans you are buying. Common reps include:
- The seller has the authority to sell the loans. This seems obvious, but confirming the seller's legal right to transfer ownership protects you from purchasing loans that are encumbered by other agreements.
- The data provided is accurate to the best of the seller's knowledge. This representation ties back to the data tape and any supplementary information the seller provided during the offering process.
- The loans are secured by the stated collateral. If you are buying secured debt, the seller is representing that the liens are valid and enforceable.
- There is no pending litigation that would affect the loans. This protects you from inheriting lawsuits you did not know about.
- The origination documents comply with applicable laws. This is particularly important for consumer debt, where origination defects can create regulatory exposure for the current holder.
Read the reps carefully. Some sellers provide broad, buyer-friendly representations. Others limit their reps to narrow, qualified statements — "to the best of seller's knowledge" or "based on information provided by the prior servicer." The narrower the rep, the less protection you have if a problem surfaces after closing. If the reps are thin, factor that into your pricing. Loans purchased with limited representations carry more risk and should be priced accordingly.
Post-Sale Remedies
The LPSA should specify what happens if a representation turns out to be false after closing. Common remedies include:
- Loan putback. The buyer can return a loan to the seller for a refund of the purchase price if a material rep is breached. This is the strongest protection available. Look for the putback window, which varies widely from agreement to agreement.
- Price adjustment. Instead of a full putback, the seller agrees to refund the difference between the purchase price and the adjusted value.
- Cure period. The seller gets a defined period to correct the issue before the buyer can exercise a putback.
Negotiate for the broadest remedies you can get. A strong putback provision with a reasonable window is the single most valuable post-sale protection in note investing. It transforms a permanent loss into a recoverable one.
Closing Mechanics and Escrow
The LPSA also governs the mechanics of closing — when funds are due, how they are transferred, when escrow releases occur, and what triggers the legal transfer of ownership. Standard terms include:
- Wire transfer of funds on the specified closing date
- Escrow hold for any loans with outstanding issues (missing documents, pending assignments, etc.)
- Servicing transfer timeline — when the loans will be boarded onto your servicer's platform
- Document delivery deadlines — when the seller must ship the physical collateral files to you or your custodian
Pay particular attention to the escrow provisions. If there are loans in the trade where the collateral file is incomplete or an assignment needs to be recorded, the LPSA may call for a portion of the purchase price to be held in escrow until the seller delivers the missing items. This protects you from paying full price for loans that are not yet fully transferable.
How Does the Closing Timeline Typically Work?
Once both parties agree on final pricing and the LPSA is signed, the closing process follows a predictable sequence:
- LPSA execution. Both parties sign the agreement. This is a binding contract — once you sign, you are committed to fund at the agreed price, subject to any remaining conditions in the contract.
- Wire transfer. You send funds on the date and terms the LPSA sets.
- Document delivery. The seller ships the original collateral files — the physical notes, mortgages, and assignments — to your designated custodian or directly to you. The LPSA specifies the delivery deadline.
- Assignment recording. The seller executes assignments of mortgage transferring each loan from the seller's entity to yours. These assignments are recorded in the relevant county. Some sellers handle recording; others leave it to the buyer.
- Servicing transfer and borrower notices. The loans are boarded onto your servicer's platform, which means transferring the data, the payment history, and the borrower communication records; how long that takes depends on the servicer. Federal rules require notice to the borrower: the old and new servicers each send a notice of transfer, the old one at least 15 days before the transfer takes effect and the new one within 15 days after (12 CFR 1024.33), and a buyer who acquires more than one mortgage loan in a 12-month period must send the borrower a notice of the ownership change within 30 days (12 CFR 1026.39).
- Post-closing reconciliation. Any escrow holdbacks are resolved as the seller delivers missing documents or completes outstanding assignments. Payments received between the sale date and the servicing transfer date are reconciled and forwarded to the buyer.
The process from LPSA execution to fully boarded loans can take weeks or months, depending on the size of the trade and the efficiency of the parties involved.
What Separates Professional Sellers from Unfamiliar Sellers at This Stage?
The distinction between professional sellers and lenders who have not previously sold loans on the secondary market — a distinction that shaped how you structured your initial bid — continues to matter at the finalization stage.
Professional Sellers
With professional sellers, the due diligence-to-close process is well-established. They expect fades. They have LPSA templates. They understand reps and warranties. The conversation is efficient because both sides speak the same language. Your focus should be on speed, documentation quality, and maintaining the relationship for future trades. Professional sellers track which buyers close smoothly and which ones create friction — and those records determine who gets first look at the next tape.
Sellers New to the Secondary Market
With sellers who have not transacted before, you will likely need to be more hands-on. They may not have an LPSA template, in which case you can provide one. They may not understand why you are fading pricing, in which case your documented evidence becomes an educational tool as much as a negotiation tool. They may not have a process for executing assignments or shipping collateral files, in which case you may need to walk them through the mechanics.
This extra work is an investment in the relationship. A seller who has a positive first experience selling loans is far more likely to come back to you with the next portfolio. And because they are not working with other secondary market buyers, you may be building an exclusive pipeline that generates deal flow for years.
How Do Acquisitions and Due Diligence Work Together?
The acquisitions workflow and the due diligence workflow are deeply intertwined — so much so that separating them into distinct processes is somewhat artificial. Your indicative bid was informed by pre-bid research. Your due diligence was ordered based on the terms of your indicative offer. Your final pricing is the product of compiling due diligence results back into the pricing model that generated your original bid. And the LPSA you negotiate is shaped by what your due diligence uncovered about the specific loans in the trade.
Understanding this interconnection is important because it affects how you allocate time and resources. You should not be completing due diligence in a vacuum and then trying to figure out how the findings affect your deal. The pricing model and the due diligence findings should be updating in parallel, so that by the time your vendor reports are complete, your final offer is nearly ready to submit.
The investors who move through this process efficiently — ordering reports promptly, merging data systematically, communicating with the seller proactively, and submitting a well-documented final offer ahead of schedule — are the ones who build the reputations that produce sustainable deal flow. The finalization stage is where all the analytical work of due diligence meets the relational work of acquisitions, and executing it well is what separates a completed trade from a missed opportunity.
 Free Note Investor Workshop
Learn notes by pricing one.
Analyze a training loan modeled on a real deal, then submit practice offers on loans that actually sold.
- No credit card
- No email needed to start
- 7 steps · about 70 min