What Does a Mortgage Note Look Like? An Annotated Example
What a mortgage note looks like: an annotated sample note, the eight parts worth reading, and how a note differs from a mortgage or deed of trust.
A mortgage note is the borrower's signed promise to repay a home loan. It's short (the standard Fannie Mae/Freddie Mac fixed-rate note runs three pages). And it's a separate document from the mortgage or deed of trust, which pledges the house as security for that promise.
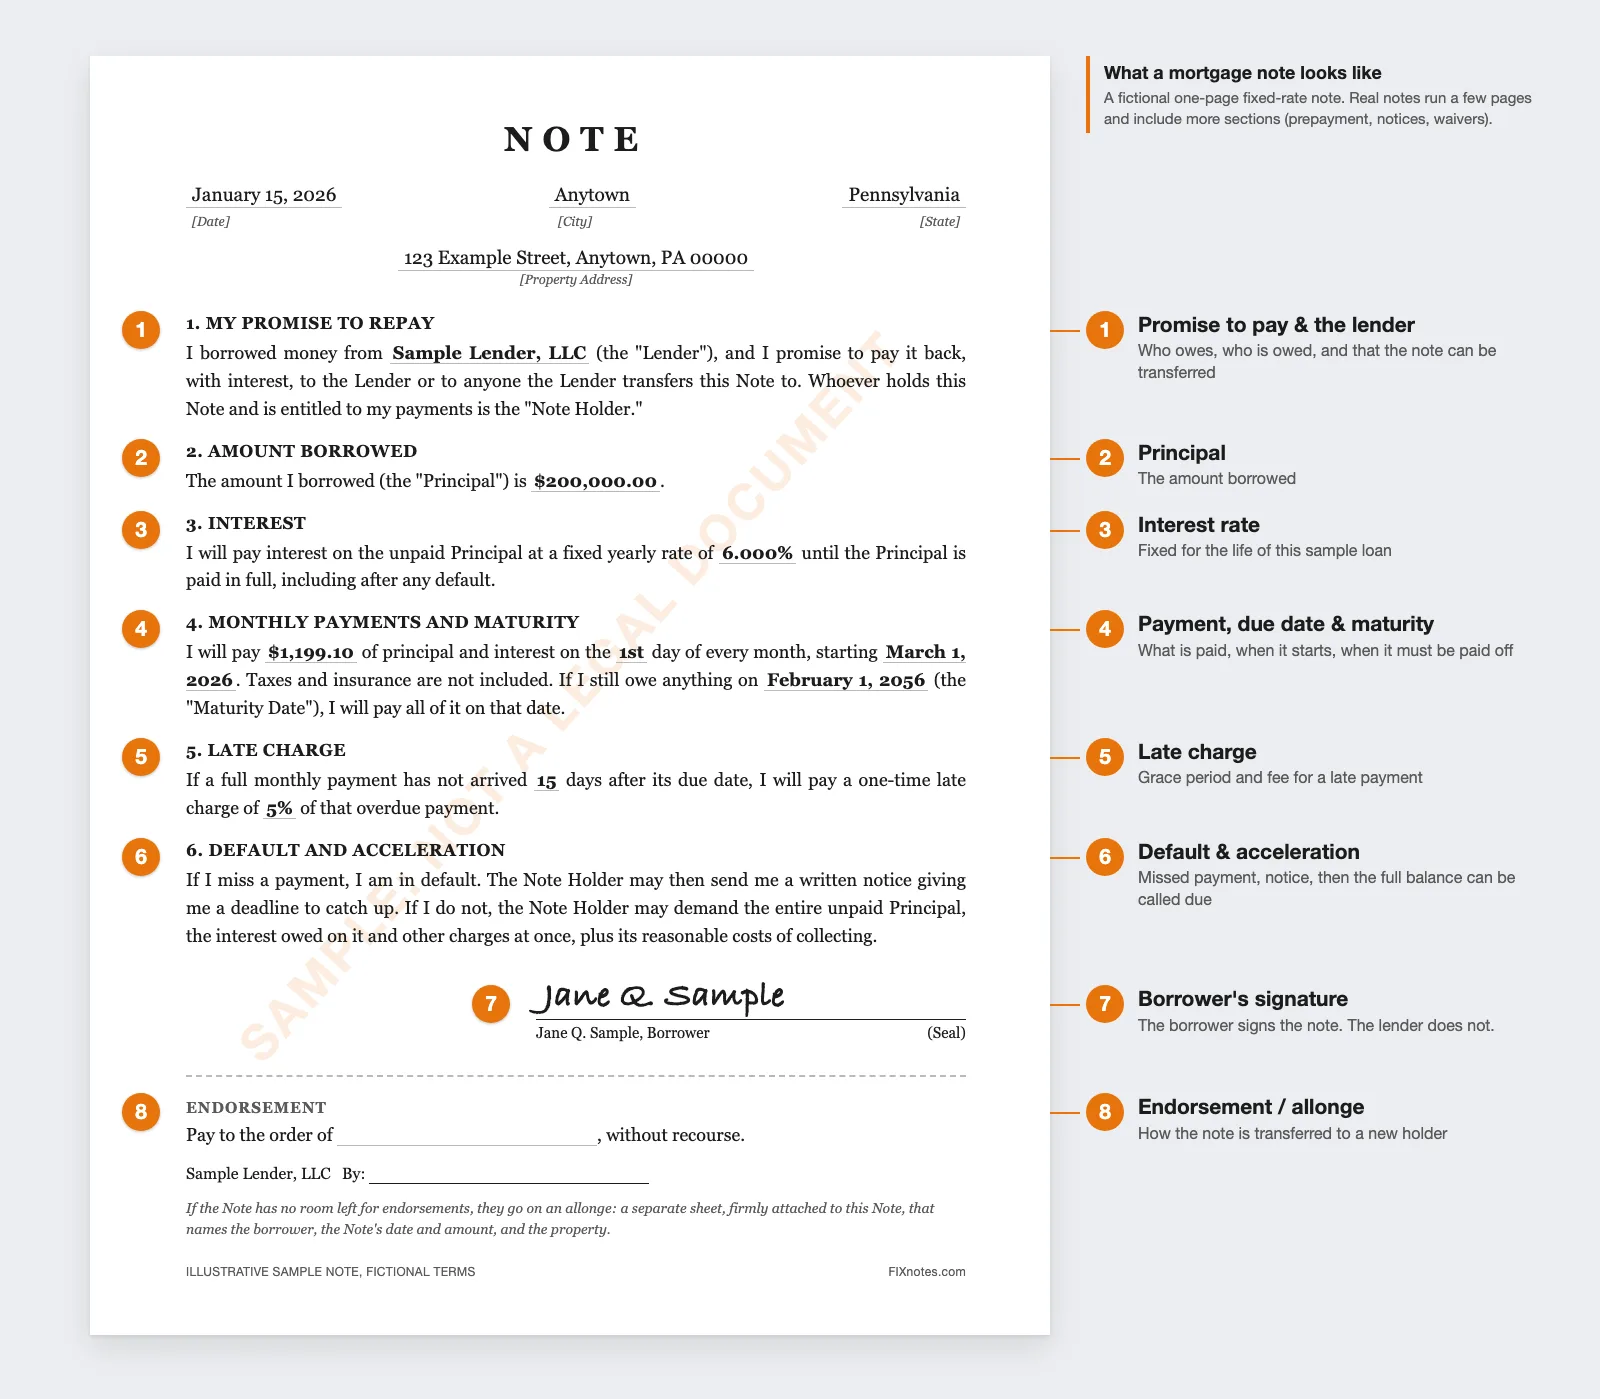
An illustrative sample drawn by FIXnotes, with fictional names and numbers. It is not a legal form. The real thing is the standard Fannie Mae/Freddie Mac uniform note (Multistate Fixed Rate Note, Form 3200, revised 07/2021).
Reading a Note, Callout by Callout
Our sample fits on one page because we cut it down. The uniform note it's modeled on has ten numbered sections plus a signature block. Every note you buy will look a bit different, but the order is usually familiar. Here is what each callout marks and where the same terms sit in Form 3200.
1. The promise to pay and the lender. The first section names the lender and says the borrower will repay. In the uniform note this is Section 1, "Borrower's Promise to Pay." It also carries a line every note investor should know by heart. "I understand that the Lender may transfer this Note." Whoever takes the note by transfer and is entitled to the payments is the "Note Holder" - the seat you sit in when you buy a loan.
2. Principal. This is the amount borrowed. Form 3200 defines it inside Section 1 ("a loan in the amount of U.S. $… (the 'Principal')"). It's the original amount, so it will rarely match the unpaid principal balance on a tape years later.
3. Interest rate. Section 2, "Interest," sets the yearly rate. The uniform note adds that the same rate applies "both before and after any default." You'll lean on that line when you calculate what a delinquent borrower owes.
4. Payment amount, due date and maturity. In the uniform note this is Section 3, "Payments." Part (A), "Time and Place of Payments," sets the day of the month, the first payment date and the maturity date. Part (B), "Amount of Monthly Payments," sets the payment. The form says the payment "does not include any property taxes, insurance, or other charges."
5. Late charge. Section 6 is "Borrower's Failure to Pay as Required." It opens with (A) "Late Charges for Overdue Payments." The grace period and the percentage are blanks the lender fills in (the 15 days and 5% in our sample are made up). Our late fee entry covers how these get applied.
6. Default and acceleration. This is still Section 6. Under (B) "Default," a borrower who doesn't pay the full monthly payment on its due date is in default. Under (C) "Notice of Default," the Note Holder can send a notice and demand the full balance if the borrower doesn't catch up. The deadline "must be at least 30 days after the date on which the notice is mailed to me or delivered by other means." That right to call the whole loan due is the acceleration clause. Section 10, "Uniform Secured Note," adds one more trigger. The security instrument can require payment in full if the property is sold or transferred without the lender's consent.
7. Signature. The form ends with "WITNESS THE HAND(S) AND SEAL(S) OF THE UNDERSIGNED" and three lines marked "Borrower." Below them sits the instruction "Sign Original Only." Only the borrower signs. That instruction is why there should be exactly one signed original - and why it's worth so much to whoever owns the loan.
8. Endorsement and allonge. Form 3200 has no endorsement section of its own. Endorsements get added when the note is sold, usually on the last page. Fannie Mae's Selling Guide says "the endorsement must appear on the note" and allows an allonge for it if certain requirements are met. The allonge must be "permanently affixed to the related note." It also has to name the borrower, the note date, the note amount and the property address. Section 8 of the uniform note, "Obligations of Persons Under This Note," says an endorser is obligated too. An endorsement marked "without recourse" avoids that (more on it below).
The sample skips four sections you'll see on the real form. They are Section 4 "Borrower's Right to Prepay," Section 5 "Loan Charges," Section 7 "Giving of Notices" and Section 9 "Waivers."
Note vs. Mortgage vs. Deed of Trust
"Mortgage note" and "mortgage" often get used for the same thing. They are two different documents signed at the same closing. Section 10 of the uniform note names the second one. It's the "Security Instrument" (a mortgage, mortgage deed, deed of trust or security deed) "dated the same date as this Note." It protects the Note Holder if the borrower breaks the promises in the note.
| Document | What it is | Who signs it | Where it's kept or recorded |
|---|---|---|---|
| Promissory note | The promise to repay, with the amount, rate, payments and default terms | The borrower | The note holder or a document custodian keeps the original in the collateral file |
| Mortgage | A security instrument that pledges the property. The borrower is the "mortgagor" | The borrower | Recorded in the public land records |
| Deed of trust | A security instrument. The borrower grants the property to a trustee "in trust, with power of sale" | The borrower | Recorded in the public land records |
Those roles come from the uniform security instruments themselves (Fannie Mae's Pennsylvania mortgage, Form 3039, and California deed of trust, Form 3005). In the deed of trust, the borrower is the "trustor" and the lender is the "beneficiary." In the mortgage, the lender is the "mortgagee." Both forms carry a "Space Above This Line For Recording Data" at the top. Fannie Mae's Selling Guide makes the seller/servicer responsible for the "accurate and timely preparation and recordation of the security instrument." Which of the two a loan uses depends on the state - that's a question for your title company or attorney on each deal (not a blog post).
The note itself usually isn't recorded. Fannie Mae's Selling Guide lists the "original note and note addenda" as documents a custodian "takes into physical custody." Its custodial package rules even say not to include any mortgages or deeds of trust.
The Two Transfer Documents
Two documents means a sale needs two transfers.
The assignment of mortgage moves the security instrument to the new owner. It's usually recorded too. For an assignment out of MERS, for example, Fannie Mae's Selling Guide tells the servicer to "record the executed assignment in the public land records." If you're new to that step, our guide to recording the assignment of mortgage walks through it.
The endorsement (on the note or on an allonge) moves the note itself, and it travels with the original paper. Under the Uniform Commercial Code, which each state has adopted in its own version, a note payable to a named person is negotiated by "transfer of possession of the instrument and its indorsement by the holder" (UCC 3-201). Possession and signature go together.
Where Is My Mortgage Note?
If you're a homeowner looking for your own note, the short answer is that the company you pay each month may not have it. The CFPB says "the servicer you pay every month may not own your mortgage." You can call your servicer, look it up online, or send a written request asking who owns the loan. Per the CFPB, the servicer "has an obligation to provide you, to the best of its knowledge," the owner's name, address and phone number. And when the loan is transferred, "the new owner is required to send you a notice." The CFPB's page on finding who owns your mortgage also links a sample letter.
The original note itself usually sits with the owner or its document custodian. It isn't at the county.
Why the Original Matters When You Buy a Note
For an investor, the original note is the asset. UCC 3-301 lists who can enforce a note, and first on the list is "the holder of the instrument." Being the holder starts with possessing it: UCC 1-201 defines the holder as "the person in possession" of a note payable to bearer or to that person. A clean original with an unbroken chain of endorsements is the simplest way for you (or your attorney) to show the right to enforce the loan when a borrower stops paying.
That's why the big buyers are strict about it. For loans it buys, Fannie Mae wants "the original note endorsed 'in blank' and without recourse." It also wants "no break in the chain of endorsements." A blank endorsement names no one. Under UCC 3-205 it makes the note "payable to bearer," and it can then be negotiated by transfer of possession alone until it is specially indorsed (for example, when a name is written in). "Without recourse" means the endorser isn't liable to pay if the borrower doesn't (UCC 3-415).
When the original goes missing, you're not necessarily stuck. It costs time and money to prove your right to enforce, though. What happens if the promissory note is missing covers the lost note affidavit and how to protect yourself before you buy.
Where the Note Fits in Note Investing
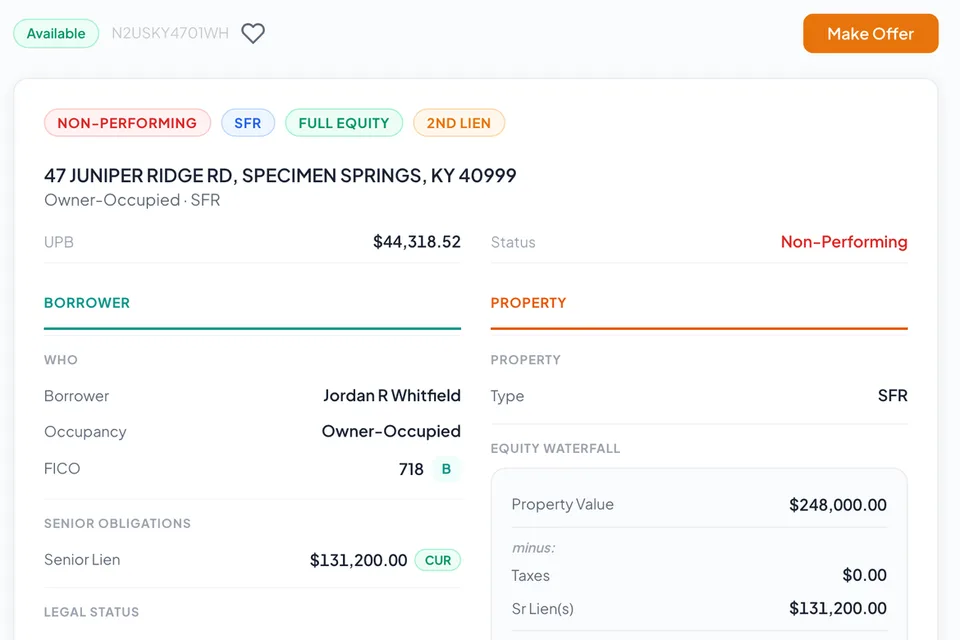
Everything above is the paper side of note investing. When you buy a mortgage note, you buy the note, the security instrument and the transfer documents that connect them. The borrower's obligation doesn't change. Only the name of who they owe does.
Loans get bought and sold after they're made, and the market where that happens is the secondary mortgage market. "Secondary" doesn't mean a second lien - it means any sale after the loan was made. Individual investors mostly see two kinds of loans there. Non-performing loans are loans where the borrower has stopped paying. Re-performing loans defaulted, got worked out (often with a modification or a repayment plan) and are paying again.
Either way, "becoming the bank" means stepping into the Note Holder's seat from Section 1. You get the lender's rights under the note, plus the lender's duties under federal and state law. A servicer collects the payments and talks to borrowers for you. Our complete guide to investing in mortgage notes picks up from there with sourcing, pricing and due diligence.
A Five-Point Check Before You Buy
When the collateral file arrives, trust but verify. Lay the note next to the data tape and check these five things.
- The terms. The borrower name, property address, original principal, rate and maturity date match the tape and the recorded security instrument.
- The signature. Every borrower line is signed, and you're looking at the original (or the seller can tell you where it is).
- The endorsements. They run unbroken from the original lender to the seller. The last one is in blank or made out to you.
- The allonge, if there is one. It's attached to the note and names the borrower, date, amount and property.
- The assignments. The recorded assignments of mortgage tell the same ownership story as the endorsements.
If all five line up, the paper is doing its job. If one doesn't, that's not automatically a deal killer - it's a cost, and it belongs in your price. The Notes 101 lesson on what a note is goes deeper on each document. The lesson on the life cycle of a note maps what happens to the paper from purchase to payoff.
Frequently asked questions
- Is a mortgage note the same as a promissory note?
- Yes. A mortgage note is a promissory note for a home loan: the borrower's signed promise to repay. The uniform security instruments define the Note as "the promissory note" the borrower signed. What makes it a mortgage note is the separate mortgage or deed of trust that pledges the property as security for that promise.
- Who holds the original mortgage note?
- The owner of the loan, or a document custodian holding it for the owner. For loans Fannie Mae buys, an approved custodian takes physical custody of the original note. Your servicer may not own your loan, but it has to tell you who does, to the best of its knowledge, if you ask.
- What is an endorsement on a mortgage note?
- A signature on the note (often with words like "Pay to the order of") that transfers it to a new holder. Under the Uniform Commercial Code, which each state has adopted in its own version, an endorsement that names the new holder is a special endorsement (UCC 3-205), and one that names nobody is a blank endorsement, which makes the note payable to whoever holds it. "Without recourse" means the endorser is not liable to pay the note if the borrower doesn't.
- What is an allonge?
- A separate sheet attached to the note that carries endorsements, usually because the note itself has no room. Under the Uniform Commercial Code (UCC 3-204, in each state's own version), a paper affixed to the instrument counts as part of it. Fannie Mae requires an allonge to be permanently affixed and to identify the note by borrower name, note date, note amount and property address.
 Free Note Investor Workshop
Learn notes by pricing one.
Analyze a training loan modeled on a real deal, then submit practice offers on loans that actually sold.
- No credit card
- No email needed to start
- 7 steps · about 62 min