Should You Pay Off Your Mortgage or Invest It?
Pay off your mortgage or invest the difference? The answer depends on the rate spread, your risk tolerance, and how much you can influence your returns.
The Debate That Never Dies
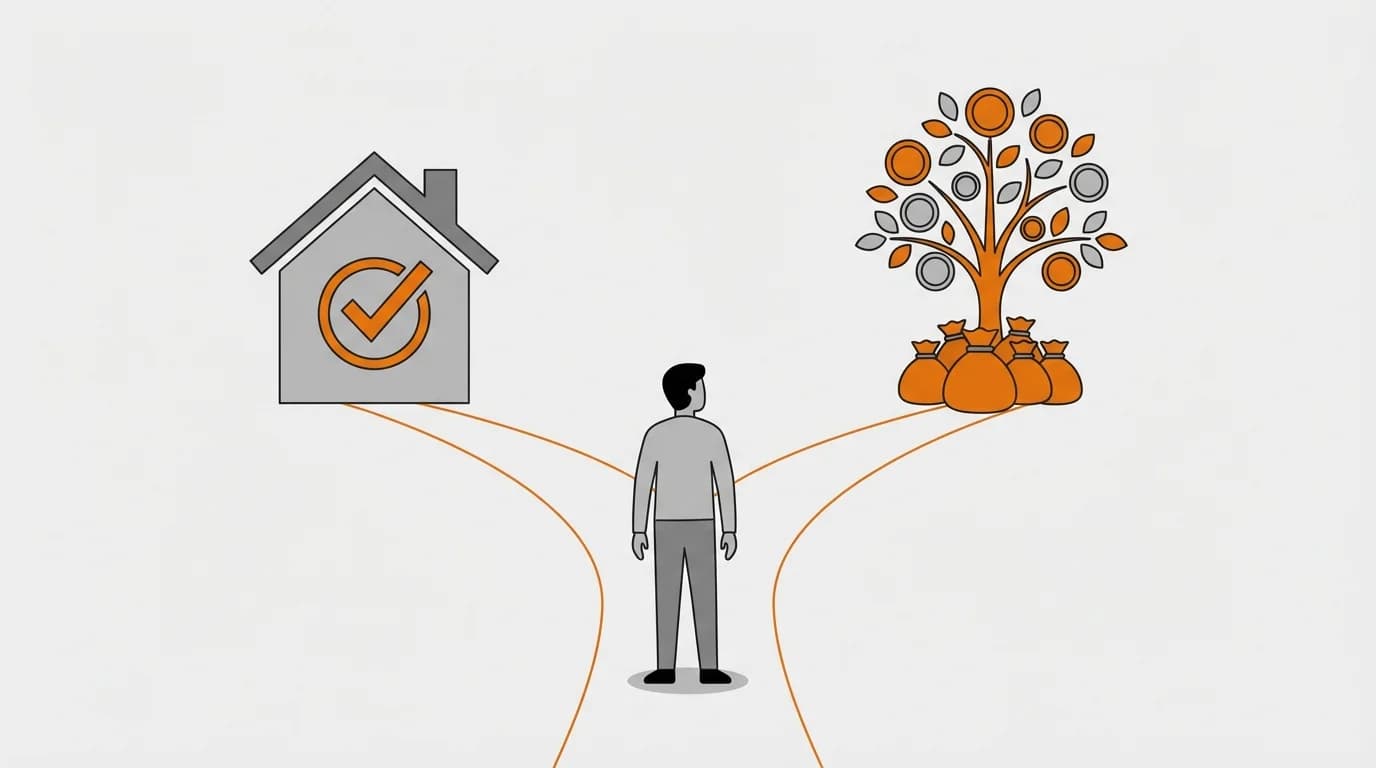
Few personal finance questions generate more heat -- and less clarity -- than this one: if you have the cash to eliminate your mortgage, should you do it, or should you keep the money invested?
On one side, you have the Dave Ramsey camp. Get out of debt, the house included: Ramsey's Baby Steps have you pay off all debt except the house first, then pay off your home early while you invest 15% of household income for retirement. Debt is risk. Debt is stress. A paid-off home is a guaranteed return equal to whatever interest rate you were paying. Sleep well at night.
On the other side, you have the spreadsheet optimizers. If your fixed-rate mortgage costs you 4% and the S&P 500 has returned about 10% a year compounded since 1928, dividends included (NYU Stern historical returns data), the math is obvious. Keep the cheap debt. Deploy the capital where it earns a higher return. The delta is free money.
Both sides have a point. Both sides are also missing something important. The answer depends on who you are, how you invest, and whether you are a passive participant in the market or someone who can actively influence the return on your deployed capital.
The Dave Ramsey Thought Experiment
Ramsey has a reframing of the question that cuts through the noise. On his show he put it like this: if your house were paid for and your financial planner told you to borrow $300,000 against it to invest in a good mutual fund, your gut answer would be an emphatic no.
Run the same test with bigger numbers. Imagine you have a $500,000 mortgage and $2.5 million in investments. The standard analysis compares the cost of the mortgage against the expected return on the investments. If the investments earn more than the mortgage costs, keep the mortgage. Simple arithmetic.
Now flip the scenario. Imagine you pay off the mortgage. You now own your home free and clear. You have $2 million invested. No debt. Would you then walk into a bank and take out a new $500,000 mortgage against your paid-off home -- just so you could have $2.5 million invested instead of $2 million?
Ramsey's bet is that you would say no: you would not voluntarily take on a half-million-dollar liability to capture a few percentage points of spread. The psychological weight of deliberately choosing debt feels different from the passive inertia of keeping debt you already have.
That reframing is powerful because it exposes the role of behavioral bias in what most people treat as a pure math problem.
Why the Simple Math Is Technically Correct
Before going further, the spreadsheet argument deserves its due. The arithmetic is not wrong.
| Scenario | Mortgage Rate | Assumed Investment Return | First-Year Spread on $500K (pre-tax) |
|---|---|---|---|
| Low-rate environment | 3.5% | 9% | +$27,500 |
| Mid-rate environment | 5.5% | 9% | +$17,500 |
| High-rate environment | 7% | 9% | +$10,000 |
If you hold a fixed-rate mortgage at 3.5% and your investments compound at 9%, every dollar used to pay down the mortgage instead of investing it "costs" you 5.5% per year. Over a 30-year amortization schedule, that spread compounds into a substantial difference in terminal wealth.
The math favors keeping the mortgage under three conditions:
- Your borrowing rate is meaningfully lower than your investment return. A 3% mortgage versus a 9% return is a wide spread. A 7% mortgage versus a 9% return is not.
- You actually invest the difference. The math only works if the capital you would have used to pay off the mortgage is deployed productively. If it sits in a savings account earning 1%, you lose.
- You maintain the investment position through volatility. The S&P 500's long-run average includes stretches of more than a decade -- 1929 to 1943, 1966 to 1982, and 2000 to 2012 -- when its return after inflation was roughly zero or negative (NYU Stern annual returns data). If you panic-sell in a downturn, the theoretical spread evaporates.
Why the Simple Math Is Not Enough
Here is what the spreadsheet misses.
Sequence-of-Returns Risk
From 1928 through 2025, the S&P 500 returned about 10% a year compounded, dividends included (NYU Stern historical returns data). But averages hide brutal variance. From the start of 2000 through the end of 2013 -- the dot-com crash, the 2008 crisis and the recovery -- the same series compounded at about 3.6% a year, barely above the cost of a cheap mortgage. If you were counting on a 9% return during that window to justify keeping your mortgage, the math did not work out the way the spreadsheet promised.
Averages are not guarantees. The order and timing of poor returns matters enormously, especially if you are drawing on the portfolio for living expenses or making decisions based on the assumption that the spread will always be positive.
The Emotional Cost of Debt
Numbers on a spreadsheet do not carry emotional weight. A mortgage payment does. Every month, that obligation arrives regardless of what the market did, regardless of whether your business had a good quarter, regardless of whether you feel secure or anxious.
For some people, the psychological benefit of owning their home outright -- the reduction in baseline financial stress, the elimination of one fixed obligation -- is worth more than the theoretical 3-5% annual spread. That is not irrational. Financial stress can cloud decisions, and clouded decisions cost money in ways that do not show up on a balance sheet.
The Difference Between Passive and Active Returns
This is the factor that changes the entire calculus for entrepreneurs and active investors.
The standard comparison pits mortgage interest against passive market returns -- an index fund, a target-date retirement account, something you buy and hold. In that context, the spread between a 4% mortgage and a 9% average return is the entire argument.
But if you are an active investor -- someone buying non-performing loans, building a note business, or investing in assets where you can directly influence the outcome -- the return profile is fundamentally different.
The ROI on a non-performing note depends on what you paid for it and how it resolves, not on what the index did that year. Buy well and resolve well, and the return can sit far above a mortgage rate; misjudge the collateral or the borrower, and it can sit below it. The number that matters is your own track record. If it shows returns several times your mortgage rate, the spread is not a rounding error. It is transformative.
The question is not "should I pay off my 5% mortgage or earn 9% in an index fund?" The question is "should I eliminate cheap leverage or deploy that capital into assets where I can influence the outcome and have a record of beating my borrowing cost by a wide margin?"
For active investors with that record, the math usually favors keeping the cheap debt and deploying the capital.
When Paying Off the Mortgage Makes Sense
The keep-the-mortgage argument is not universal. There are clear situations where prepayment is the right move.
You are not actually investing the difference. If the capital freed up by not paying off the mortgage is sitting idle, earning negligible returns, or being spent on lifestyle inflation, the theoretical spread does not exist. Pay off the mortgage. At least you capture a guaranteed return equal to the interest rate, or your after-tax rate if you itemize and deduct mortgage interest (IRS Publication 936 sets out who can).
Your mortgage rate is high. Freddie Mac's weekly average for a 30-year fixed mortgage has stayed between about 6% and 7.8% since mid-September 2022 (Freddie Mac PMMS historical data), and at those rates the spread narrows dramatically. Paying off a 7% loan earns a guaranteed 7%. The stock market's long-run average is higher, but it comes with no guarantee in any given decade. The higher the rate, the more attractive payoff becomes.
You are approaching retirement with no active investment strategy. If you are shifting from wealth accumulation to wealth preservation, the guaranteed elimination of a fixed expense has real value. A paid-off home takes the mortgage payment out of your monthly cash needs in retirement, though property taxes and insurance remain.
The debt creates genuine financial stress. If the mortgage is causing you to lose sleep, make worse decisions in other areas of your life, or avoid taking calculated risks in your business because you feel over-leveraged, the emotional cost exceeds the mathematical benefit. Remove it.
Your equity position is already strong. In the example above -- a $500K mortgage against $2.5 million in investments -- the mortgage equals 20% of the portfolio. Paying it off still leaves $2 million invested. The peace of mind may be worth more than the marginal return on that last $500K.
When Keeping the Mortgage Makes Sense
Your rate is low and fixed. A 3-4% fixed-rate mortgage is some of the cheapest capital available to an individual. In an inflationary environment, you are paying back the loan with dollars that are worth less than the ones you borrowed. That is a structural advantage.
You are an active investor with a proven track record. If you consistently generate returns that meaningfully exceed your borrowing cost -- through note investing, real estate, or business operations -- every dollar deployed into your strategy is worth more than a dollar used to eliminate cheap debt.
You have strong cash flow and the mortgage is easily serviceable. If your monthly mortgage payment represents a small fraction of your income or cash flow, the debt is not creating risk. It is creating optionality. You maintain access to capital that can be deployed when opportunities arise.
You understand and accept the risk. Keeping the mortgage and investing the difference is a leveraged position. Leverage amplifies returns in both directions. If you understand that and have the financial cushion to absorb temporary drawdowns without being forced to sell, the math favors staying invested.
A Framework for the Decision
Rather than picking a side in the Ramsey-versus-spreadsheet debate, use this decision framework:
Step 1: Calculate Your True Spread
Subtract your mortgage rate from your realistic expected return -- not the historical average, but the return you have actually been earning or can reasonably project.
- Spread greater than 5%: Strong case for keeping the mortgage
- Spread of 2-5%: Moderate case; weigh emotional and risk factors
- Spread less than 2%: Weak case; the guaranteed return of payoff becomes competitive
Step 2: Assess Whether You Are Passive or Active
| Investor Type | Return to Plan On | Spread vs. 5% Mortgage | Leans Toward |
|---|---|---|---|
| Index fund investor | About 10% a year compounded since 1928 (NYU Stern data), with no guarantee in any decade | About 5 points if history repeats, before taxes | Depends on risk tolerance |
| Active note investor | What your own track record shows | Your record minus 5 points | Keep the mortgage only if your record clears the rate by a wide margin |
| Cash sitter | Your savings or CD rate | Negative whenever that rate is below 5% | Pay off the mortgage |
Step 3: Evaluate Your Emotional Baseline
Be honest about how debt affects your decision-making. If carrying a mortgage causes you to underinvest, avoid reasonable risks, or lose sleep, the behavioral cost exceeds the mathematical benefit. There is no shame in optimizing for peace of mind.
Step 4: Consider the Rate Environment
Interest rates change the equation materially. Freddie Mac's 30-year fixed average was 2.96% across 2021 and 7.28% on October 1, 2026 (Freddie Mac PMMS historical data). The borrower who locked in about 3% in 2021 has a very different calculus than one financing near 7%. As rates rise, the case for aggressive payoff strengthens. As rates fall, the case for maintaining leverage and deploying capital elsewhere strengthens.
What This Means for Note Investors
For readers of this site, the mortgage payoff question has an additional dimension.
When you invest in mortgage notes, you are literally on the other side of this trade. You are the lender. You collect the interest that borrowers pay. Understanding the borrower's psychology around debt -- the emotional weight, the desire to be mortgage-free, the willingness to make sacrifices to eliminate the obligation -- is not abstract. It is the foundation of how loan modifications, prepayments, and resolution strategies work.
The borrower who prioritizes paying off their mortgage over investing is, in many cases, your customer. They are the homeowner who will scrape together a lump-sum payoff to eliminate a non-performing loan. They are the borrower who will accept a modification with a slightly higher payment because being current on their mortgage matters to them on a level that transcends the spreadsheet.
Understanding both sides of this debate -- the mathematical case for leverage and the behavioral case for debt elimination -- makes you a better investor. It informs how you price assets, how you structure modifications, and how you evaluate the likelihood of different resolution outcomes. If you want to see what sitting on the lender's side of that trade involves, start with how to invest in mortgage notes, and compare it with owning property in rental properties vs. note investing.
Making the Call
There is no universally correct answer to whether you should pay off your mortgage or invest the difference. The right answer depends on your borrowing cost, your investment skill, your emotional relationship with debt, and the rate environment.
What is universally true is this: the worst thing you can do is keep cheap debt and then fail to deploy the capital productively. If you are going to carry a mortgage, the freed-up capital must be working -- not sitting idle, not leaking into lifestyle spending, not parked in a savings account earning less than your borrowing cost.
For passive investors, the decision is closer than most spreadsheet enthusiasts admit. The theoretical spread between mortgage rates and market returns is real but fragile -- it depends on sequence of returns, time horizon, and the investor's ability to stay the course through volatility.
For active investors -- particularly those building a note investing business with a track record of returns well above their mortgage rate -- the math is not close. Cheap, fixed-rate debt is a tool. Use it. Deploy the capital into assets where you can influence the outcome and add value.
Dave Ramsey is not wrong. He is giving advice calibrated to people who need guardrails. If you are the kind of person reading a site about mortgage note investing strategy, you are probably not the person those guardrails were built for. Know the math, respect the psychology, and make the decision that aligns with both your financial position and your capacity to put capital to work.
Frequently asked questions
- Should I pay off my mortgage or invest?
- It depends on the spread between your mortgage rate and the after-tax return you can reliably earn, how much risk you can carry, and how you feel about debt. A low fixed rate favors investing the difference; a high rate, a short horizon or a strong aversion to debt favors paying it off.
- Is paying off a mortgage a guaranteed return?
- In one sense, yes: every extra dollar of principal saves your mortgage rate on that dollar for the rest of the loan, with no market risk. If you itemize and deduct the interest, the saving is your after-tax rate, which is lower. The trade-off is liquidity. Money in home equity can't cover an emergency or fund a better opportunity without a sale or a new loan.
- What should I do with the money if I keep my mortgage?
- Put it to work at a return above your borrowing cost after taxes and fees. Capital that sits idle while you carry the mortgage costs you the spread every month.
Take the free Note Investor Workshop — analyze a training loan modeled on a real deal, then submit practice offers on loans that actually sold. No credit card.